"I own tech, healthcare and consumer stocks. How did they all fall together?"
Perhaps you did spread it out. That still leaves a question: spread across what?
A hawker with three stalls
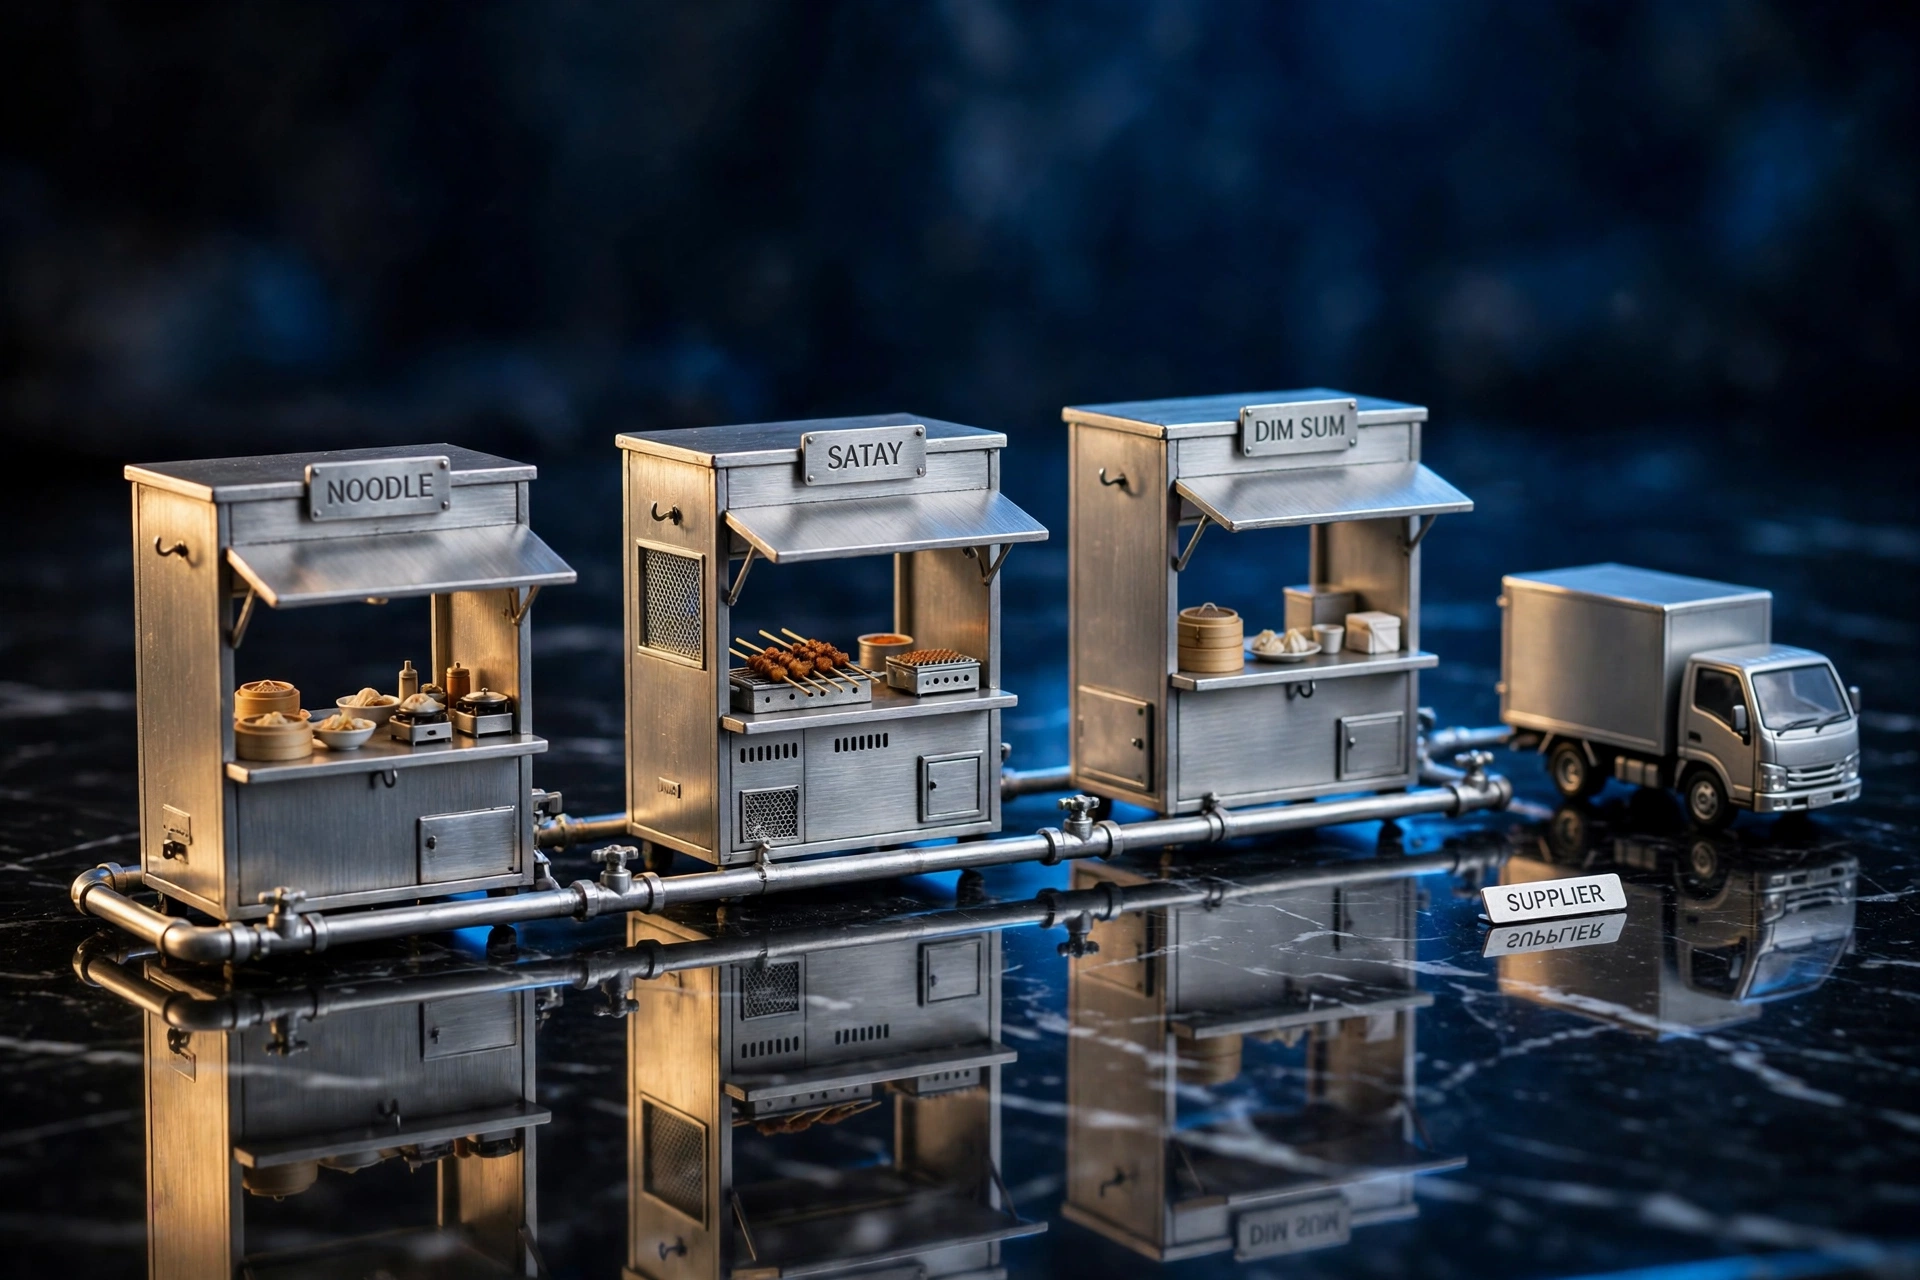
Consider a hawker in a food court. He runs three stalls. Chicken rice at $4 a plate. Laksa at $5 a bowl. Drinks at $2 a cup.
Different menus. Different customers. Different prices.
"Different stalls, different food," he says. "What could go wrong?"
His partner looks at the delivery schedule. "Nothing, until the lorry does not come."
All three stalls share one gas supply. All three share one chicken supplier. The supplier's lorry is late one morning. The gas delivery is late too.
The chicken rice stall has no chicken. The laksa stall has no gas to cook the broth. The drinks stall has no ice, because the ice machine runs on the same gas.
Three stalls. Three menus. One lorry.
That is the story of 5 November 2026, in a food court.
Three stalls, one supplier
On Thursday, 5 November, the S&P 500 fell 4.36% to 7,353.73. The Nasdaq Composite fell 5.52% to 24,315.00. The Dow fell 3.44%, or 1,833.06 points, to 51,523.06. AP / Informist
The Philadelphia Semiconductor Index fell 12.25%. All 30 of its constituents were down.
The Nasdaq was now 11.9% below its record close on 6 October. That is correction territory. The S&P 500 was 5.95% below its record close. That is not.
All 11 S&P 500 sectors fell on the same day. Technology fell hardest. In the Pulsafi close table, Technology fell 8.00%. Communication Services fell 0.59%. Utilities fell 0.71%. Consumer Staples fell 0.75%.
A lower fall is still a fall. It is not the same fall.
Nvidia fell 9.26% to $181.60. AMD fell 17.26%. Broadcom fell 10.43% to $291.53. Micron fell 17.46%. Oracle fell 6.93% to $115.16. Tesla fell 10.8%.
Even the Magnificent Seven fell together. Apple fell least, down 1.53%. Tesla fell most, down 10.8%. Different companies. Different prices. The same question, underneath them all.
In Asia on Friday, the selling continued in early trading. The Kospi fell sharply and trading was halted for 20 minutes by a circuit breaker. The Nikkei fell more than 5% and was more than 20% below its June peak. Those Asia figures were intraday snapshots, not final closes.
What was the question? Will the AI buildout continue, at the same speed, with the same returns?
After the US midterm elections, investors worried that Democrats would tighten regulation of the AI industry and put the brakes on new data-centre building. Senator Bernie Sanders had called for a national moratorium on building data centres. Whether that moratorium would ever happen is a different question. The market did not wait to find out.
Overlap is not the same as common exposure
Here is the awkward possibility. You may own many names, and still own one bet.
Zenith looked at a version of this on 26 October, in "Your ETFs May Be Buying the Same Stocks Again". Different ETFs can hold the same stocks. That is overlap. It is not the only problem.
Overlap, common exposure and historical correlation are three different questions. Those questions are related, but they are not interchangeable.
Overlap asks: do my funds hold the same companies? Common exposure asks: do my holdings need the same thing to go right? Historical correlation asks: how did they move together in the past?
On 5 November, Nvidia, AMD, Broadcom, Micron and Oracle were different companies. They were not different exposures. They all needed AI spending to keep rising. They all needed data centres to keep being built. They all needed the returns to justify the cost.
When that story was questioned, they fell together. Just by different amounts.
More tickers is not more safety. It is more tickers.
Suppose you own 20 stocks. Ten are chip stocks. Five are cloud providers that sell to chip buyers. Three are data-centre landlords. Two are power companies that supply data centres.
How many separate bets is that? One. With 20 names on it.
That does not mean every chip stock is the same trade. It means the trade is not diversified just because the tickers are different. ## A bearish day is not yet a broken portfolio
Morningstar, in its 2026 Diversification Landscape, puts it plainly: "Asset class correlations are dynamic. They tend to spike in bear markets, reducing risk mitigation exactly when it is needed most." Morningstar
A CFA Institute digest of 72 years of daily closes reaches the same conclusion: "Diversification benefits decrease as markets exhibit extreme performance… diversification begins to fail as a risk mitigation strategy when it is most often needed." CFA Institute
That does not mean diversification never works. It means it works least on the days you notice it most.
In normal times, stocks move for their own reasons. One company misses earnings. Another wins a contract. A third is hit by a lawsuit. Those are different shelves. A diversified portfolio smooths them out.
In a crisis, stocks move for one reason. A fear. A shock. A forced seller. A margin call. Everyone is reacting to the same thing at the same time.
The type of shock decides what hedges it. A growth shock tends to help Treasuries. Investors buy government bonds, yields fall, bond prices rise. On 5 November, the 10-year Treasury yield fell 6 basis points to 4.84%. Bonds did not make the day green. They did not fall with stocks in the same way.
An inflation shock is different. If prices are rising and rates are rising with them, stocks and bonds can fall together. That is what happened in 2022. The stock-bond correlation was positive and elevated in 2022 to 2024, before returning to negative territory in 2025, according to Morningstar.
A liquidity shock is different again. When traders need cash quickly, they sell what they can sell, not what they want to sell. Correlations can rise across almost everything.
Vanguard makes the same point from the bond side: bonds' correlation to stocks "has frequently been positive in the last several years," but if growth weakens and central banks cut rates, fixed income would act as ballast. Vanguard
Fidelity's Jurrien Timmer put the current stock-bond correlation at a positive 10–12% over five years. "Bonds have hedged stocks during growth scares but may fail during inflation shocks," he said.
A useful technology can survive a disappointing investment cycle. Shareholders do not get paid simply for recognising that the technology is useful.
That line is about AI, but it fits here too. A useful idea can survive a bad day. A portfolio does not get paid simply for owning many names.
Consider a hypothetical $10,000, split eleven ways
Consider a hypothetical $10,000. Split it equally across all 11 S&P 500 sectors. That is about $909 in each.
Use the Pulsafi close table for 5 November. Technology -8.00%. Communication Services -0.59%. Utilities -0.71%. Consumer Staples -0.75%. Real Estate -1.82%. Health Care -2.50%. Financials -2.87%. Materials -2.91%. Energy -2.98%. Consumer Discretionary -3.83%. Industrials -4.12%.
Add those eleven falls together and divide by eleven. The average fall is about 2.83%.
Your hypothetical $10,000 would be worth about $9,717 at the close. Down $283.
A hypothetical $10,000 in the S&P 500 itself would be worth about $9,564. Down $436.
The equal-weight basket did better by about $153. Not because it was magic. Because the index is cap-weighted, and technology — the sector that fell hardest — is a large part of the index. The equal-weight basket owned less of the worst stall.
All three examples exclude borrowing fees, dividends, commissions and execution costs. They are arithmetic examples, not current prices or proposed trades.
Now the counter-case. If technology had been the best sector that day, equal-weight would have lagged the index. Pretending that benefit does not exist would be just as misleading as pretending it is free.
The point is not that you should have owned Communication Services. You could not have known that in advance, and tomorrow the ranking could reverse. The point is that "diversified" is a statement about weights and drivers, not about the number of tickers in your account.
What would make diversification more convincing
Here is a useful check before the next purchase. Not a list of traps. A list of evidence questions.
First, what shock am I facing, in one sentence? On 5 November, a reasonable answer was: "Fear that AI regulation and data-centre delays will slow AI spending." If you cannot name the shock, you cannot know what should hedge it.
Second, what did each holding actually do on 5 November, holding by holding? Treasuries rallied that day. Bitcoin fell 5.98% to $75,599, so it did not diversify that day.
Third, do my holdings need the same thing to go right? Group them by driver, not by ticker. AI spending. Consumer spending. Interest rates. Oil prices. If three groups collapse into one driver, you have one bet, not three.
Fourth, what is my invalidation and loss budget? At what point would I admit the thesis is wrong, not just early? How much can I lose on this portfolio, in total, and still sleep and still trade tomorrow? If a 2.8% fall already breaks the budget, the problem is size, not diversification.
Fifth, open the fund. Look through it. Add your direct exposure to a stock to your indirect exposure through every fund that holds it. Write down the total, in dollars and as a percentage. Then ask what could damage several holdings at once.
If your plan only works when correlations stay low, your plan does not work when you need it most.
"I can always wait," a trader says, about the decision to sell. That is a weak risk plan. Price can force timing first. A margin call, a loss budget, a bill that cannot wait — any of those can make the decision for you.
Selling after a fall does not test diversification. It tests your loss budget. If you sell at the bottom because it fell 2.8% when the index fell 4.4%, you have not proved diversification failed. You have proved your position size was too big, or your loss budget too small.
Back to the hawker
Back to the food court. The lorry is late. The gas is late. The three stalls are quiet.
The hawker has a choice. He can blame the stalls. He can say the food was wrong, the prices were wrong, the customers were wrong. Or he can look at the delivery schedule, and ask how much of his day depended on one lorry.
The stalls may reopen when the lorry comes. The question is whether the owner knew, before that morning, how much of his day depended on one lorry.
You do not get paid for owning many names. You get a result from the exposures you actually carry.