Your broker sends a notification: dividend received.
Money has arrived without you selling a single share. Very nice. Surely that means the investment just became more profitable?
Not necessarily.
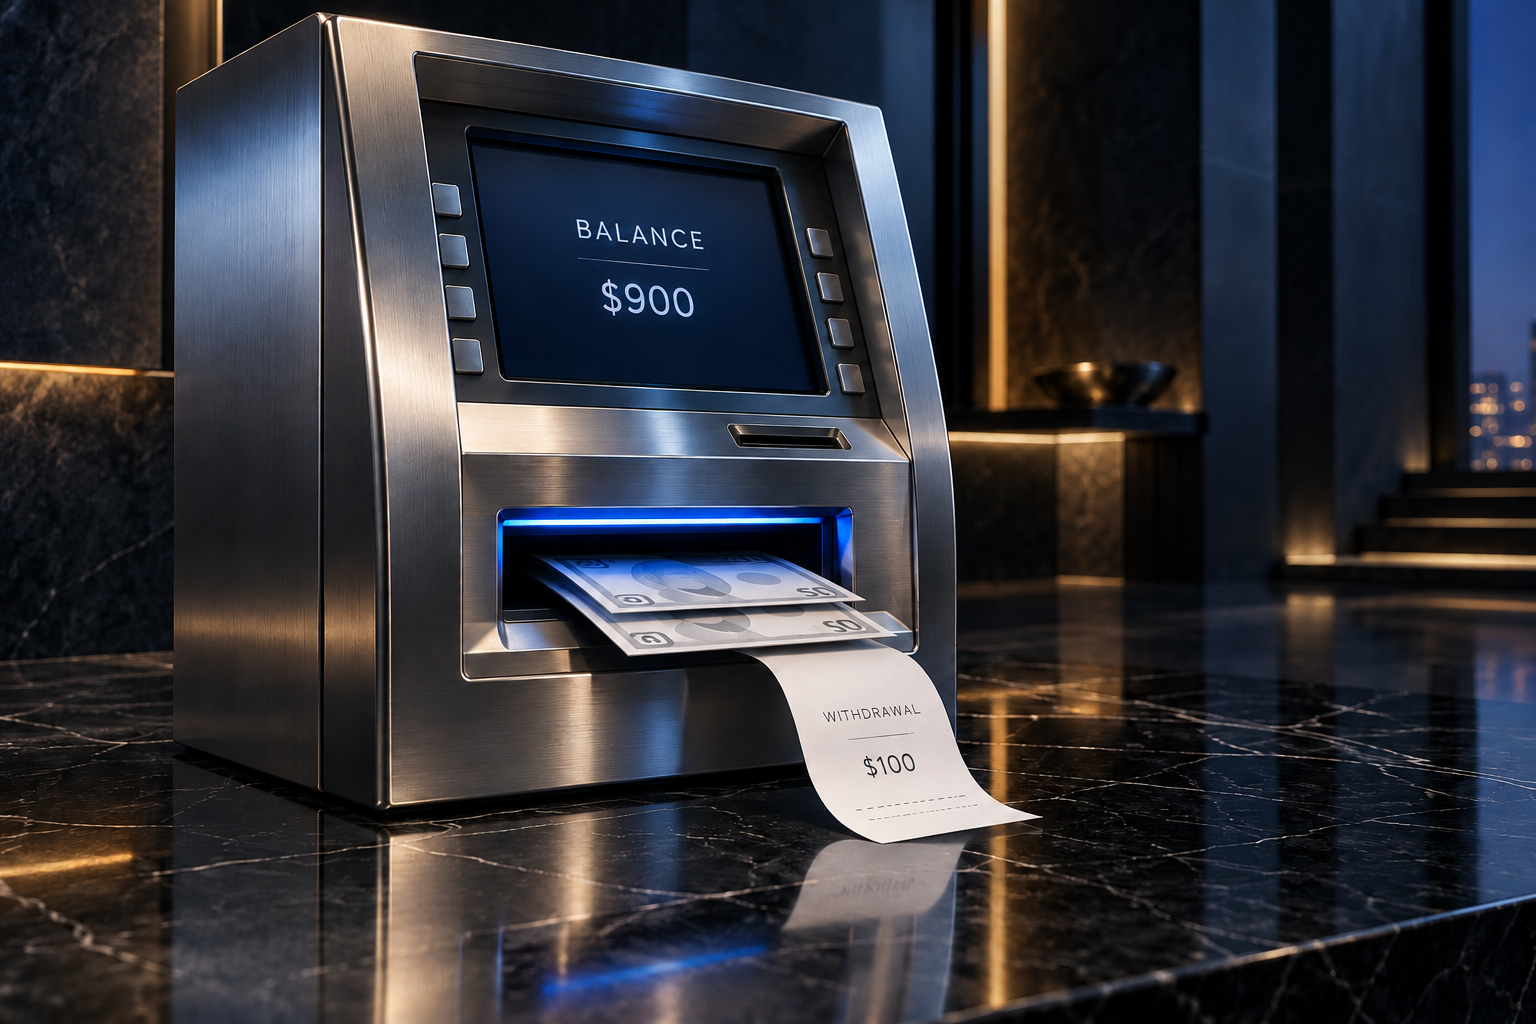
Imagine withdrawing $100 from an ATM. You count the notes, put them in your wallet and announce, “Good morning. I made $100.”
Your friend looks at the receipt.
“Your bank balance went down by $100.”
“Yes, but look how much cash I have now.”
Nobody would confuse that withdrawal with a salary. Yet a dividend notification can encourage a surprisingly similar mistake: noticing the cash that arrived while ignoring what happened to the asset it came from.
A company is more complicated than a bank account. It can earn profits, lose customers, borrow money and grow. The comparison is about one thing only: moving value into your pocket is different from creating new value.
That distinction matters whether you buy dividend stocks for income or trade around their payment dates.
First, follow the money
A cash dividend transfers money from a company to eligible shareholders. Once distributed, that cash is no longer available inside the business to fund operations, repay debt or finance investment.
That does not make the payment bad. It means the payment has a source.
Suppose, purely for illustration, you own 100 shares priced at $50. Your holding is worth $5,000. The company declares a $1 cash dividend per share.
You are entitled to $100. But someone buying the shares after the relevant cutoff will not receive that same payment. They are buying a different package of rights.
Holding everything else constant, the simple ex-dividend value comparison is:
- Before: 100 shares at $50, worth $5,000.
- After: 100 shares at $49, worth $4,900, plus a $100 dividend entitlement.
- Combined value: still $5,000, before taxes and trading costs.
Notice “entitlement”. The money may reach your account later, on the payment date. Do not assume it is already available to spend on the ex-dividend date.
The CFA Institute's dividend analysis describes the expected price adjustment with the important condition that everything else is unchanged.
Real markets do not politely freeze everything else. Earnings news, interest rates, orders and changing expectations can move the price at the same time. The stock might fall less, fall more or rise that day.
The $49 figure explains the mechanism. It is not a forecast of the opening quote. Nasdaq explains why actual ex-date prices can differ from the theoretical adjustment.
A dividend can put cash in your account without increasing the combined value of your investment.
The date that matters is not the notification date
For an ordinary U.S. cash dividend, the ex-dividend date tells you when a new buyer no longer receives the upcoming payment. Buying on that date or afterwards ordinarily does not qualify you; buying before it ordinarily does.
The record date identifies the shareholders on the company's books. The payment date is when the distribution is scheduled to be paid. These dates answer different questions.
Check the actual corporate-action notice rather than reconstructing the timetable from memory. The SEC's investor explanation also describes exceptions for large distributions and stock dividends. Rules and settlement arrangements differ across markets.
That is why “buy before payday, collect the dividend, then sell” is incomplete reasoning.
Other market participants can see the payment too. You have not discovered a secret ATM that the rest of the market forgot to visit.
A dividend-capture trade needs an advantage beyond collecting the payment: its entry price, exit price, execution costs, tax treatment and market risk must work together. The calendar alone does not supply that advantage.
Count the whole result
Suppose you buy the same 100 shares at $50, qualify for the $1 dividend and later sell at $48.50.
Your sale brings in $4,850. The dividend contributes another $100. Total proceeds are $4,950 against a $5,000 purchase.
You lost $50, or 1%, before costs and taxes.
The $100 dividend was real. So was the $150 share-price loss. Celebrating one while excluding the other changes the story, not the result.
FINRA explains total return as including the investment's change in value and income. For a simple holding with no extra purchases, the useful arithmetic is ending value plus dividends, minus starting value and relevant costs.
Keep currency consistent too. A dividend paid in U.S. dollars and a portfolio measured in Singapore dollars cannot be added without accounting for conversion. Your broker's income screen and performance screen may also cover different periods.
None of this means a lower share price proves a poor investment. A price-only chart can understate the experience of someone who received distributions. Equally, a large income number can hide a shrinking investment.
Use both sides of the ledger.
A higher yield can arrive for the wrong reason
Dividend yield is a ratio, not a quality certificate.
Imagine a company paying an annual dividend of $2 per share. At a $50 share price, that is a 4% yield. If its price falls to $25 while the quoted annual dividend remains $2, the displayed yield becomes 8%.
The company has not doubled the payment. The denominator has halved.
That might represent an attractive price, deteriorating expectations or something in between. The yield itself cannot tell you which.
Now suppose the annual payout is subsequently cut to $1. The forward yield at $25 becomes 4%. Someone who bought at $50 still receives only $1 per share, and the market value of the holding remains far below their purchase price in this example.
Before comparing yields, check what the displayed number uses: the past year's payments, the latest regular payment multiplied into an annual figure, or an estimate. A one-off special dividend should not quietly become a promise of recurring income.
The useful question is: “What cash payment am I reasonably expecting, and what would make that expectation fail?”
So why would anyone want dividends?
Because income has a purpose, and companies do not always have a good use for every dollar they retain.
An investor funding regular expenses may prefer cash distributions to arranging periodic sales. A mature business may have limited attractive expansion opportunities. Returning surplus cash can be more sensible than spending it on a fashionable acquisition just because management wants a bigger empire.
Those are practical reasons to value a dividend policy. They do not require pretending the payment appears from nowhere.
There is also a possible discipline benefit: a commitment to distribute cash can force managers to justify what they retain. But the incentive can cut both ways. Protecting a prestigious payout can tempt a business to borrow, sell assets or neglect investment.
These are possible mechanisms, not proof about a particular company. A dividend financed partly by borrowing is not automatically reckless; context matters. Borrowing repeatedly to support a payout that the business cannot sustain deserves much closer examination.
Likewise, retaining every dollar is not automatically superior. The question is what the company can earn by keeping it, compared with what shareholders give up.
The investment case concerns the business's future cash-generating ability and the price paid for it. The dividend policy describes how some of that cash reaches shareholders.
Check the engine behind the payment
You do not need a spreadsheet with 47 tabs to start. Three checks will take you further than sorting a screener by the highest yield.
First, can the ordinary business support the payout? Read the cash-flow statement and the company's explanation of its dividend policy. Compare cash generation over several periods with investment needs and distributions. One strong quarter or an asset sale can make a weak pattern look healthy temporarily.
Second, what else needs that cash? Debt maturities, essential maintenance and expansion compete for the same resources. A payout that looks comfortable before those demands may look different afterwards. The appropriate measures vary by business; a bank and an industrial manufacturer should not be forced into the same simplistic cash-flow test.
Third, what happens if business weakens? Consider a lower payout, not just the advertised one. Does the investment still make sense if income falls and the share price also declines? Common-stock dividends are not guaranteed, so do not budget them as though they were guaranteed salary.
The SEC's guide to reading a 10-K explains where to find operating results, risks and management discussion in a U.S. company's annual report. Use the report to test the story, not merely decorate it with a payout ratio.
Reinvestment changes the destination, not the origin
Reinvesting dividends can increase the number of shares you own. Those extra shares can participate in future returns and future distributions. That is useful, but it is not an immediate multiplication trick.
If the illustrative $100 dividend buys shares at $49, it purchases about 2.04 additional shares, assuming fractional shares are available and ignoring costs. You would own about 102.04 shares worth $5,000 at that price.
You have more shares than before. You have not instantly become richer than the original $5,000 position. Future results depend on what the investment does next, and the actual reinvestment price may differ because payment comes later.
For performance comparisons, check whether a chart or return series already includes dividends and assumes reinvestment. Adding the cash again would count the same distribution twice. A raw share-price chart and a dividend-adjusted series answer different questions.
Count the cash once. Count the remaining asset honestly. Then judge the investment.
Back at the cash machine
The ATM receipt is not bad news. You wanted spending money, and now you have it.
You simply would not judge your finances by the thickness of your wallet while refusing to look at your bank balance.
Treat dividends with the same honesty. Enjoy the payment. Understand what funded it. Measure what remains.