“If I buy more now, I can get out at a lower price.”
The arithmetic can be correct. The conclusion can still be dangerous.
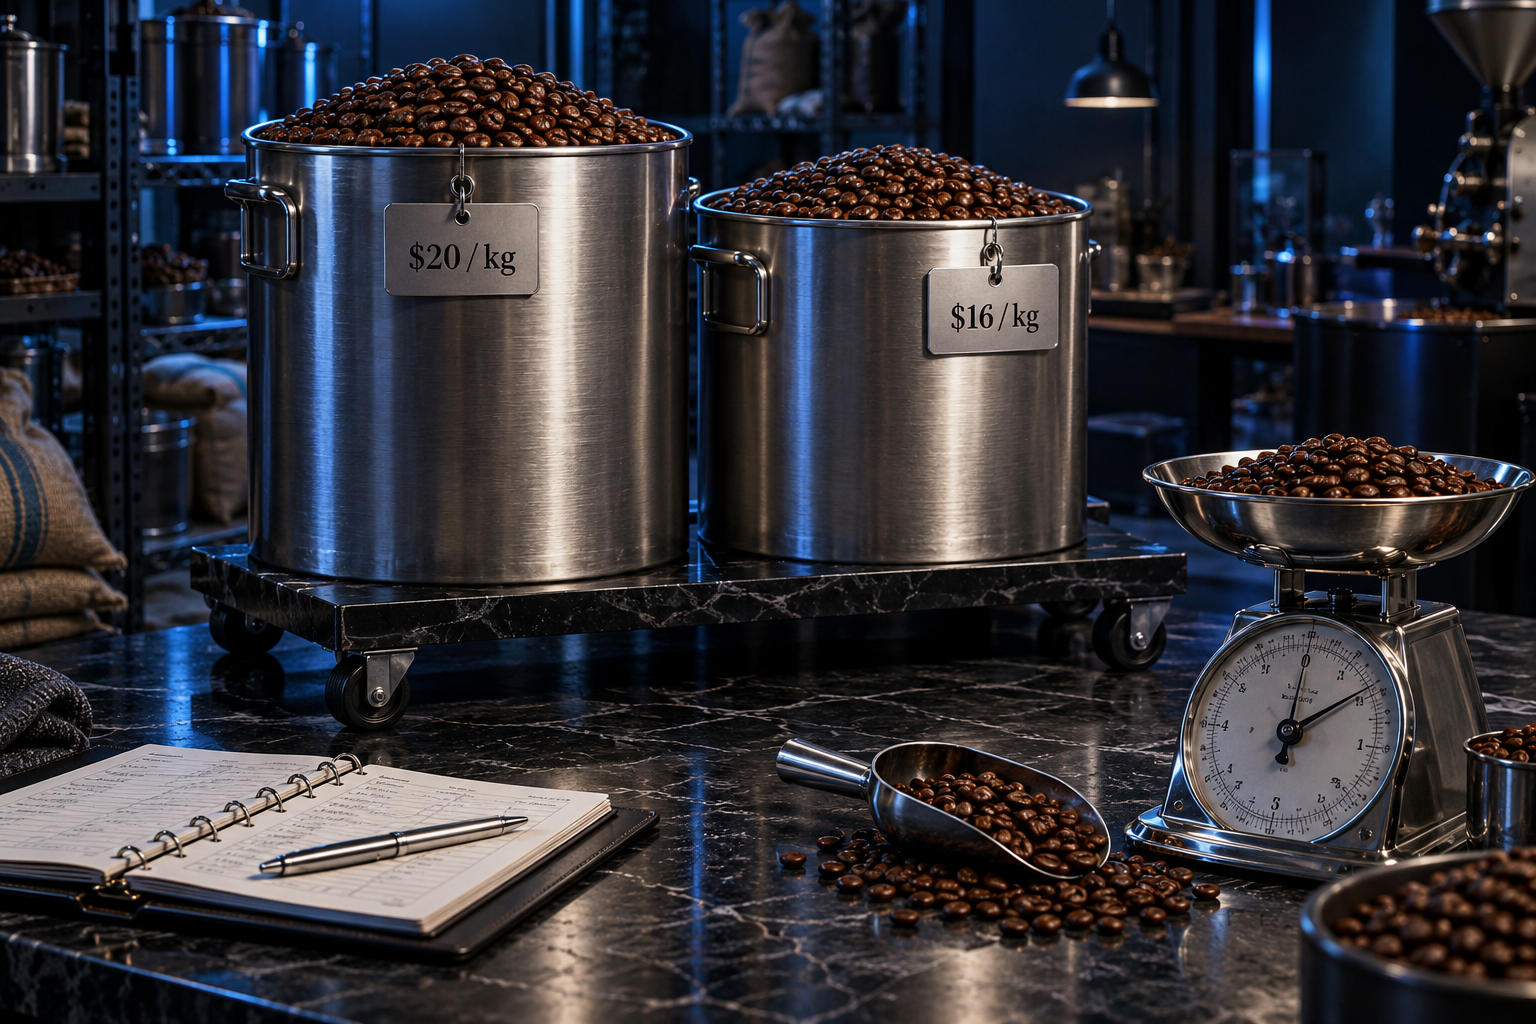
Imagine a café owner who bought a large batch of coffee beans at $20 a kilogram. A week later, the same supplier offers them at $16.
“Good news,” he tells his partner. “If we buy the same amount again, our average cost becomes $18.”
His partner looks at the crowded storeroom.
“Lovely. Are we selling twice as much coffee?”
Suddenly, the conversation becomes less comfortable. The lower average is real. So are the extra beans, the cash tied up and the demand needed to justify the purchase.
Shares do not spoil like coffee beans, and owning a business is different from running a café. But the decision has a similar trap: a nicer average can distract you from a larger commitment.
Before averaging down, separate three things: what happened to the old loss, what the new purchase adds, and whether you would want that larger position today.
The loss does not disappear when the average improves
Consider a hypothetical stock. Ignore fees, spread, taxes, dividends and interest on cash throughout these examples. These are fully paid shares, not leveraged positions.
You buy 100 shares at $100. Your cost is $10,000.
The share price falls to $80. Your holding is worth $8,000, leaving a $2,000 unrealized loss.
You then buy another 100 shares at $80, spending $8,000 more. You now own 200 shares costing $18,000. Your average purchase price falls to $90.
At the same $80 market price, those shares are worth $16,000.
Your unrealized loss is still $2,000.
Nobody refunded the original loss. You added $8,000 of shares worth $8,000 at the moment of purchase. Before transaction costs, that exchange creates no immediate gain.
The displayed percentage loss improves from 20% of $10,000 to roughly 11.1% of $18,000. The denominator grew. Your wealth did not recover by the difference between those percentages.
A lower average cost can make the account look healthier before a single dollar has been recovered.
This matters because an account screen can provide emotional relief while quietly increasing financial exposure. The red percentage becomes smaller precisely when more money is committed to the same uncertain outcome.
A nearer breakeven comes with a larger position
There is a genuine benefit to buying cheaper: the combined position now breaks even at $90 rather than $100, before costs.
From $80, that requires a 12.5% rebound instead of 25%. Pretending this benefit does not exist would be just as misleading as pretending it is free.
The price of the nearer breakeven is another $8,000 exposed to the stock.
If the price reaches $90, the original shares still lose $1,000. The new shares gain $1,000. Together they break even. The second purchase offsets the first loss; it does not rewrite the first purchase.
If the price falls to $70, the original shares lose $3,000 and the new shares lose another $1,000. The combined loss becomes $4,000.
For a fair comparison, start both choices with the same resources: the original shares plus $8,000 available cash.
| Future share price | Keep 100 shares and $8,000 cash | Add 100 shares and keep no cash |
|---|---|---|
| $70 | $15,000 total value | $14,000 total value |
| $80 | $16,000 total value | $16,000 total value |
| $90 | $17,000 total value | $18,000 total value |
This is the trade-off stripped of the comforting average. Buying more improves the outcome if the new purchase rises and worsens it if the new purchase falls.
Every $1 move now changes the shareholding's value by $200 instead of $100. That doubles this position's dollar sensitivity to price, not necessarily every measure of risk across your entire portfolio.
Judge the next purchase without asking it to rescue the first
A useful question is: “If I held no shares today, would I want to buy this amount at $80?”
Not “Would I like my old money back?” That answer is rarely controversial.
The new 100-share purchase has its own outcome: 100 multiplied by the difference between the future price and $80. Its attractiveness depends on what happens from here, not on your desire to return to the old entry price.
Your original cost still matters for recordkeeping and potentially taxes. It does not, by itself, tell you what buyers will pay next month.
Ask what changed when the price fell. Was it a broad market decline while the business evidence remained broadly intact? Or did a key customer leave, financing become harder or the original growth assumption weaken?
These are different situations. A lower price can improve prospective value if the underlying prospects are sufficiently unchanged. If those prospects deteriorated faster than the price, “cheaper than I paid” may still be expensive.
For a technical trade, use the same discipline with chart evidence. Has the original setup survived, or are you replacing a failed trade with an investment story because selling feels unpleasant?
A business thesis and a chart setup are different frameworks for a decision. Switching between them only after the original exit condition appears makes the decision much harder to evaluate honestly.
A planned addition still needs a total risk limit
Buying in stages can be deliberate. Someone may establish a small initial position because valuation is uncertain, then add only when predefined evidence and price conditions are met.
That differs from increasing the position every time the screen turns red. But writing a plan does not make its assumptions correct.
Consider another hypothetical decision at $80. You own the original 100 shares and are assessing a downside scenario of $72. Keeping them exposes you to another $800 decline from today's price to that scenario. Adding 100 more shares makes that further decline $1,600.
If your budget for additional loss from today is $1,000, adding the full extra 100 shares does not fit. At an $8 loss per additional share, only $200 of that scenario budget remains after the existing holding, equivalent to 25 additional shares before costs.
That is an arithmetic ceiling under the stated assumptions, not a recommendation to buy 25 shares. The thesis may already be invalid, or the scenario may be too mild.
Also separate this forward-looking budget from your loss since the first purchase. At $72, the original lot alone would be down $2,800 from its $100 entry. Starting the next calculation at today's price must not make the accumulated loss vanish from your records.
A stop order cannot turn either budget into a guaranteed ceiling. The SEC explains that a triggered stop becomes a market order and the eventual fill may be substantially worse than the level you selected. A stop-limit can fail to execute. SEC order guidance
Dollar cost averaging answers a different question
“But isn't buying more when prices fall called dollar cost averaging?”
Sometimes people use the terms loosely. The decision rules matter more than the label.
Investor.gov defines dollar cost averaging as investing equal amounts at regular intervals regardless of market fluctuations. A fixed cash contribution buys more units at lower prices and fewer at higher prices. Investor.gov definition
Buying an extra block specifically because an existing trade is losing is a different trigger. It may be sensible or mistaken, but calling it DCA does not settle the question.
Diversification is a separate choice. A regular schedule can buy an individual stock as well as a fund. CIRO explicitly includes stocks in its explanation and warns that DCA neither prevents losses nor guarantees returns. CIRO guidance
Regular contributions to a diversified portfolio and repeated additions to one troubled company therefore should not inherit the same risk description simply because both involve multiple purchases.
There is another hidden connection: your stock may also sit inside your funds. FINRA highlights concentration through individual holdings, correlated assets and overlapping funds. Check the combined exposure, not just the size of the position on one screen. FINRA on concentration risk
The strongest reason to add cannot be the average
The attraction of breakeven is understandable. It offers a neat ending: recover the loss, close the position, forget the episode.
But that ending is a personal accounting milestone, not necessarily a reason for the market to turn.
In a study of 10,000 brokerage accounts from 1987 to 1993, Terrance Odean found investors more readily realized gains than losses. That is evidence about the disposition effect, not proof that every averaging-down purchase is irrational. It is a reason to examine whether avoiding a realized loss is steering the decision. Original study
Before adding, write down the current evidence, the condition that would change your mind, the proposed total position and a downside scenario. Then compare buying with retaining cash, reducing exposure or choosing another opportunity.
If the only improvement you can explain is “my average becomes lower,” you have described the accounting benefit. You have not yet explained why the new purchase deserves the money.
The next dollar needs a reason to be invested. Repairing the appearance of the last dollar is not enough.
Back to the café storeroom
The café owner may have a good reason to buy the cheaper beans. Perhaps orders are rising and the additional stock will be used promptly.
Or perhaps he is buying relief from an uncomfortable receipt.
The sensible purchase is the one justified by tomorrow's demand and today's available cash, not simply yesterday's price.
Your average cost tells you what you paid. Your next decision determines how much more you put at stake.